Setting up car insurance on auto-pay is undeniably convenient. However, treating your policy as a "set-it-and-forget-it" expense is one of the most common financial mistakes drivers make.
Insurance carriers quietly update their risk algorithms, rate structures, and discount programs every single year. Over time, an insurer that offered the most competitive pricing three years ago may now charge significantly more than market average for the exact same coverage.
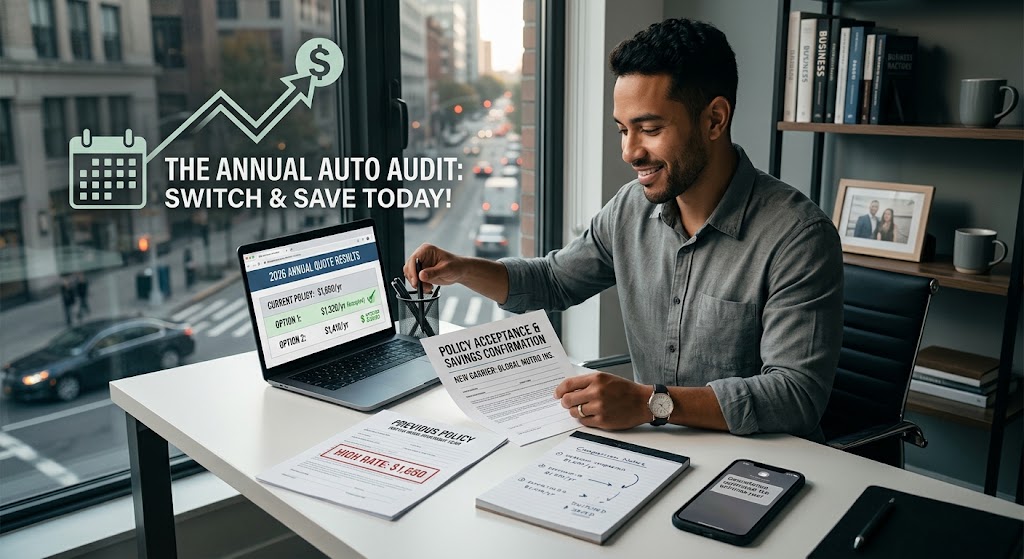
Performing an annual auto insurance audit ensures you are always paying the true market rate while maintaining complete financial protection. Here is how to master the yearly review process.
1. The Cost of "Loyalty Penalty"
Many insurance providers use pricing models known as price optimization. This practice uses data analysis to gauge how likely a customer is to shop around versus stay put.
If an insurer predicts you won't switch policies, your rates may slowly rise over consecutive renewal periods—even without any claims or traffic tickets on your driving record. Requesting competing quotes every 12 months signals to carriers that you are an active market shopper, giving you the leverage to capture better rates.
2. Match Your Policy to Your Current Life Phase
Your premium should evolve alongside your personal life. Significant savings often open up during regular life milestones:
-
Remote Work Shifts: Transitioned from a daily office commute to working hybrid or fully remote? Lowering your declared annual mileage reduces your collision risk profile and drops your rate.
-
Credit Score Improvements: In most states, insurers factor credit-based insurance scores heavily into rate calculations. If your credit score improved over the past year, your premium should reflect that change.
-
Relocation: Moving to a safer zip code, getting an off-street parking space, or reducing daily drive times lowers liability risks.
-
Vehicle Aging: As your vehicle depreciates, maintaining full collision and comprehensive coverage on an older car may no longer make financial sense.
3. The 4-Step Annual Quoting Strategy
-
Review Existing Coverage Limits: Open your current policy's Declarations Page (Dec Page). Note down your exact limits for bodily injury, property damage, and deductibles.
-
Collect 3 to 4 Apples-to-Apples Quotes: Request rates from a mix of major national carriers, regional providers, and independent brokers using your existing policy limits as a baseline.
-
Audit Available Discounts: Check for newly available savings opportunities, such as paperless billing, defensive driving course credits, telematics app enrollments, or multi-policy bundling.
-
Negotiate or Switch: Share competing lower quotes with your current carrier's retention team to see if they will match the rate. If they won't, complete the switch to the new provider without leaving a gap in coverage.
Never Miss Your Annual Review
Mark your calendar 30 days before your annual policy renewal date. Taking 15 minutes each year to re-evaluate your auto insurance keeps hundreds of dollars in your pocket while ensuring your coverage keeps up with your life.